KRX: 005930 / 000660 · DART K-IFRS
LEAD DISPATCH · KOREA DART K-IFRS & IR BREAKDOWN
Four Takeaways From Samsung Electronics' 3Q26 Memory Numbers: Reading the 7.3pp Margin Gap With SK Hynix
Following up on my SK Hynix 3Q26 note, I placed Samsung Electronics' 3Q26 DART preliminary disclosures and IR tables on the same K-IFRS frame: consolidated revenue 195.25T KRW, DS operating profit 106.5T KRW (72.4% OPM), a 75.7% mathematical boundary for Samsung Memory OPM vs. SK Hynix's 79.7%, and why the margin gap narrowed from 25.4pp to 5.8pp before widening two straight quarters to 7.3pp.
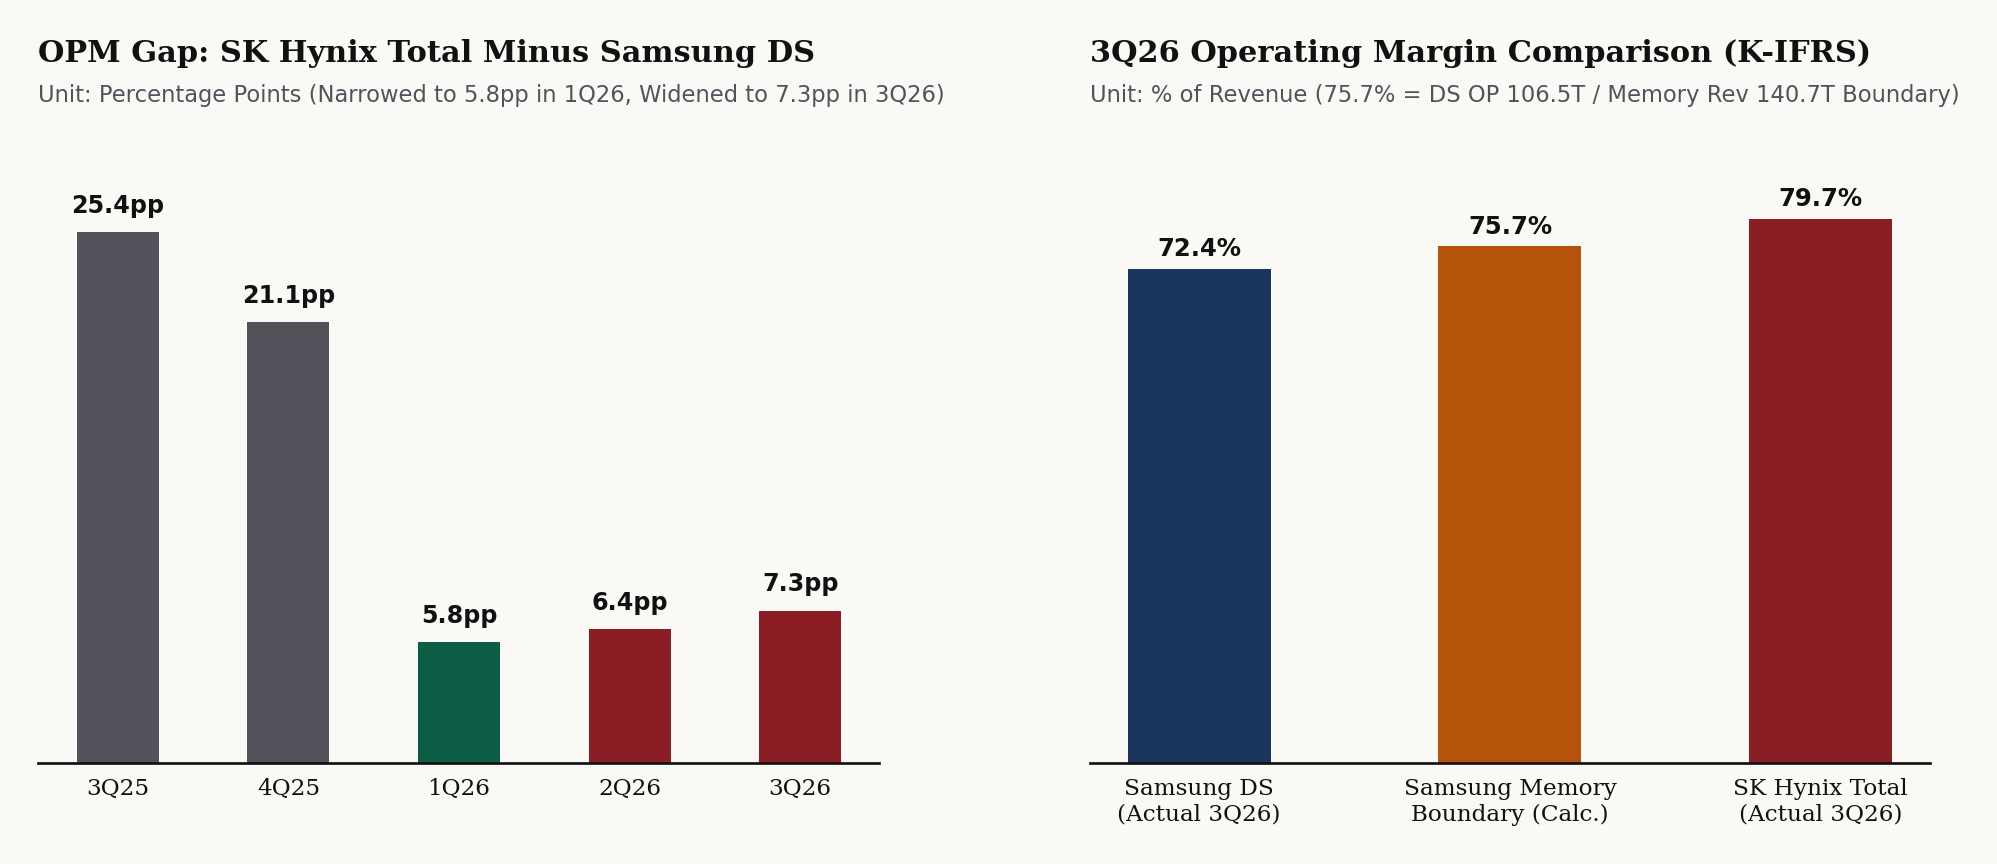
FIG 1. Five-quarter operating margin gap between SK Hynix consolidated and Samsung Electronics DS division (narrowing from 25.4pp in 3Q25 to 5.8pp in 1Q26 before widening to 7.3pp in 3Q26) and the 75.7% mathematical boundary for Samsung Memory OPM. Source: DART K-IFRS filings & 3Q26 IR decks.
- Why Scope Matters in Korean Filings: Samsung discloses standalone revenue for Memory (140.8T KRW in 3Q26) but reports operating profit only at the broader DS division level (106.5T KRW on 147.1T KRW revenue = 72.4% OPM), blending Memory with System LSI and Foundry.
- Mathematical Boundary Check: Even if System LSI + Foundry (6.3T KRW combined revenue) earned zero operating profit, Samsung Memory's standalone 3Q26 OPM is mathematically bounded at 75.7% (Calc.)—still below SK Hynix's 79.7% unless non-Memory DS booked an operating loss exceeding ~5.6T KRW.
- Next Filing Checkpoints: November mid-month DART Q3 statutory report (Segment Footnote) and 4Q26 HBM4 mass-production shipment mix.